Second home buying in Kihei can suit buyers who want regular South Maui time, a lock-and-leave retreat, and a home that supports future retirement plans. The strongest purchases begin with a realistic plan for personal use, full carrying costs, property care, and any rental activity.
More buyers want a place to escape, gather family, or plan for retirement. In Kihei, that may mean comparing a beach-area condominium, a resort-oriented residence, or a single-family home with more privacy and outdoor space.
This guide covers financing, locations, property types, ownership, rentals, and costs so you can evaluate a Kihei property based on how you plan to use it.
Why Buy a Second Home?
A Kihei second home can provide a dependable South Maui base for personal getaways, family visits, future retirement, or carefully planned rental use.
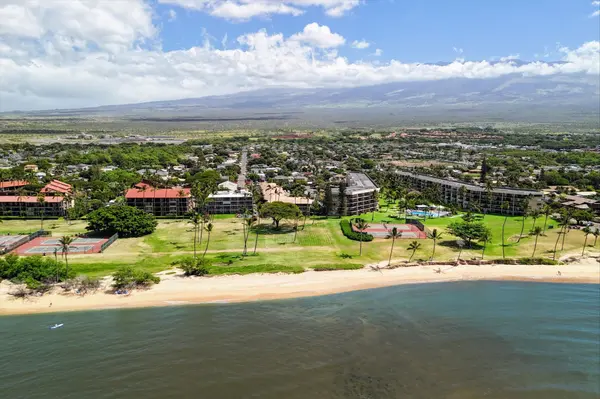
Kihei is a census-designated place and South Maui community known for sunny weather, beach access, and a broad mix of housing options. For second-home buyers, the appeal is practical as well as scenic. Many properties sit near beaches, restaurants, grocery stores, and everyday services, which can make shorter stays easier to enjoy.
Some owners want a personal retreat for several visits each year. Others expect to spend longer stretches on Maui after retirement while maintaining a mainland residence. A second home can also become a gathering place for children, grandchildren, and friends.
If rental income is part of the plan, treat it as one consideration rather than the sole reason to buy. Association policies, property classification, management costs, taxes, and occupancy patterns can all affect the ownership experience. The best fit is generally a home you would be comfortable using and maintaining even if rental conditions change.
Second Home vs. Investment Property
A second home is primarily intended for the owner's personal use, while an investment property is generally acquired with income production as the central objective.
That distinction can affect how a lender reviews occupancy, reserves, available loan programs, insurance, and tax considerations. A buyer who plans to use a Kihei condo throughout the year may approach financing differently from someone whose main goal is rental revenue.
| Consideration | Second home | Investment property |
|---|---|---|
| Primary purpose | Personal stays, family use, and future lifestyle flexibility | Income production and return objectives |
| Lender occupancy review | Owner use is central to the application | Rental use is usually central to underwriting |
| Expected rental activity | May be occasional, subject to applicable rules | Often an essential part of the ownership plan |
| Reserve planning | Should cover housing costs and periods of vacancy | Should account for operations, vacancies, and repairs |
| Tax and insurance focus | Depends on occupancy, property classification, and coverage | May involve different use, reporting, and coverage considerations |
Be candid with your lender about how often you expect to occupy the property and whether you anticipate renting it. Also confirm that the condominium association's rules match your intended use. A property marketed as visitor-friendly may still have ownership, financing, or association details that do not align with your plan.
Financing a Second Home
Financing a second home in Kihei commonly requires a larger upfront cash commitment and stronger documentation than financing a primary residence.
Lenders typically review credit, debt obligations, liquid reserves, projected housing expenses, and the property type. Maui price points also mean that many buyers consider jumbo financing, particularly for ocean-view homes, newer residences, and well-located resort-area condos.
Before touring properties, speak with lenders experienced in Hawaii transactions and second-home lending. Ask how they evaluate condominium projects, association finances, insurance requirements, and properties with rental-related characteristics. A loan option that works for one building may not be available for another.
Your budget should cover more than the monthly loan payment. Include association dues, property taxes, insurance, utilities, management or caretaking, furnishings, travel, and a maintenance reserve. Early planning is especially useful for off-island buyers, who may need to coordinate several providers from a distance.
Choosing the Right Location
The right Kihei location depends on whether you prioritize beach proximity, walkability, quieter surroundings, views, convenience, or a particular ownership style.
Kihei stretches along South Maui's coastline, so the experience can differ substantially by micro-location. Some buyers prefer being near South Kihei Road, beaches, restaurants, and daily services. Others place more value on a residential setting, larger interiors, or a home farther from busier routes.
For a second home, think through arrival and departure details. Consider parking, elevator access, storage, air conditioning, luggage handling, and how easily the property can be secured when vacant. A beautiful unit with intensive upkeep may not suit a buyer seeking simple ownership from off-island.
It also helps to visit at different times of day. Traffic patterns, wind, sunlight, nearby activity, and noise can feel different in the morning, afternoon, and evening. In a condo community, walk the parking areas and common spaces as well as the unit itself. In a single-family setting, pay attention to exterior maintenance demands, access, and how the home feels when you are away for extended periods.
Property Types and Options
Kihei offers second-home buyers condominiums, townhome-style residences, single-family homes, and resort-oriented properties with distinctly different ownership demands.
| Property type | Often suits | Advantages | Management considerations |
|---|---|---|---|
| Condominium | Buyers seeking lock-and-leave ownership | Shared exterior maintenance and amenities in many communities | Review dues, reserves, rules, parking, insurance, and potential assessments |
| Single-family home | Owners who want privacy, outdoor space, or room for larger groups | More flexibility and a more private living experience | Plan for landscaping, exterior care, utilities, and off-island oversight |
| Resort-oriented residence | Buyers who value amenities and an established visitor environment | Convenient lifestyle features and a polished arrival experience | Confirm governing documents, use restrictions, fees, and service arrangements |
Condominiums can be practical for buyers seeking lower day-to-day responsibility, but each community operates differently. Review association budgets, meeting minutes, insurance information, reserve planning, parking rules, and rental policies before making a decision.
Single-family homes can offer more privacy and flexibility, especially for extended family stays. They also create more direct responsibility for landscaping, exterior maintenance, storm preparation, utilities, and regular oversight. Buyers who live off-island should identify dependable local support before closing.
Second Home Buying in Kihei: Prices and Market Trends
Kihei pricing and demand vary meaningfully by property type, location, condition, view corridor, monthly carrying costs, and permitted use.
Island-wide figures show how differently the two main property types are moving. In September 2026, the Maui County median price was $660,000 for condominiums, up 1.1% from a year earlier, and $1.15 million for single-family homes, down 11%. For a second-home buyer, that split is a reminder to compare homes within the same ownership category rather than relying on one number.
A condo near South Kihei Road with beach access can have a very different cost structure from an inland single-family residence, even when both are positioned as second homes. The purchase price is only one part of the comparison.
For a beach-proximate condominium, examine association dues, reserve planning, building insurance, parking arrangements, elevator access, storage, air conditioning, and the rules governing guest stays or rentals. A building with strong amenities may be appealing for arrival convenience, but buyers should understand the ongoing obligations that support those amenities.
For an inland single-family home, compare privacy, outdoor space, parking, landscaping requirements, utility costs, and the need for local caretaking. These homes can work well for longer family stays, but remote ownership often involves more hands-on coordination than condominium ownership.
Resort-oriented communities may appeal to buyers who value a polished arrival experience and established visitor infrastructure. The key question is whether the property's governing documents, fees, financing profile, and permitted use fit your actual plan. Do not assume that a vacation-oriented setting automatically means unrestricted rental flexibility.
Demand is often strongest for homes that combine good condition with straightforward ownership. In the luxury segment, ocean views, privacy, walkability, upgraded finishes, parking, storage, reliable air conditioning, and manageable ownership logistics can all influence buyer interest. Recent comparable sales are most useful when reviewed alongside the individual property's condition, fees, location, and use restrictions.
Owning, Managing, and Renting
Owning a second home in Kihei is easiest when you have a realistic plan for care during the periods you are off-island.
Condominium ownership can simplify routine maintenance because exterior work and common-area services may be coordinated through the association. Owners should still understand what dues cover, how reserves are funded, and whether capital projects are planned. Association minutes, budgets, insurance information, and house rules can reveal important day-to-day ownership details.
For single-family homes, a local caretaker or property manager can help coordinate landscaping, repairs, utility issues, and storm readiness. Establishing dependable local contacts before closing can make remote ownership less stressful and help protect the property during vacancies.
Rental use requires careful property-by-property review. Maui County treats any rental of less than 180 days as a transient vacation rental, and those rentals are generally limited to hotel-zoned districts. Bill 9, signed in December 2025, phases out short-term rental use in apartment-zoned condominiums, and the deadline for Kihei properties is January 1, 2031. A follow-up measure, Bill 88, created new hotel zoning classifications that some buildings can apply for, but that review is still underway and no outcome should be assumed. Do not assume a home can be rented for short stays simply because it is near a resort area or was previously marketed for visitor use. Confirm the permitted use for the specific property before treating rental income as part of the purchase plan, and consider asking a Hawaii real estate attorney to review the building's status.
Taxes and Ongoing Expenses
The full cost of a Kihei second home includes financing, taxes, insurance, association dues or maintenance, utilities, management, and periodic repairs.
Property tax is the line that most often surprises mainland buyers. Under Maui County's FY2026-27 rates, non-owner-occupied residential property is taxed at $6.25 per $1,000 of net taxable assessed value up to $1 million and $9.00 per $1,000 from $1 million to $2.5 million, compared with $1.65 per $1,000 for a primary residence that qualifies for the homeowner exemption. A second home does not qualify for that exemption, so budget at the non-owner-occupied rates and confirm the current classification with the County.
Use this ownership checklist when evaluating a property:
- Loan payment and lender-required reserves
- Real property tax classification and applicable county rules
- Homeowners, condominium, flood, wind, and personal-liability coverage as applicable
- Association dues, special assessments, and reserve-related considerations
- Utilities, internet, smart-home monitoring, and security
- Management, caretaking, cleaning, landscaping, and pest control
- Furnishings, appliance replacement, and a repair reserve
- Travel and coordination costs for off-island ownership
Insurance deserves early attention, particularly for coastal properties and condominium communities. For a condo, determine what the association policy covers and what coverage may be needed for the unit interior, contents, and personal liability.
These expenses may look manageable individually, but together they can materially change the annual cost of a part-time home. Build a conservative budget before comparing properties solely by purchase price.
Second Home Buying in Kihei: The Buying Process Step by Step
The second-home buying process in Kihei begins with a clear use plan, then moves through financing, property selection, document review, negotiations, and closing coordination.
- Define your use plan. Identify when you expect to visit, how many people the home should accommodate, your maintenance tolerance, and whether rental use is essential or optional.
- Set a realistic purchase range. Review financing, reserves, and estimated ownership costs before becoming attached to a particular property.
- Focus the search. Prioritize homes that fit both your lifestyle and ownership requirements. For condos, review association restrictions early.
- Evaluate the complete property picture. Consider comparable sales, condition, seller disclosures, monthly costs, management needs, parking, insurance, and the property's permitted use.
- Coordinate closing carefully. Hawaii transactions have local practices and contract considerations that can feel unfamiliar to mainland buyers. Off-island buyers can often complete much of the process remotely, but consistent communication with the lender, escrow team, insurance contacts, and local representatives is essential.
Second home buying in Kihei works best when location, budget, and intended use all line up. A condo near the beach may suit low-maintenance visits, while a private home may better serve buyers seeking more space and flexibility.
Look beyond the view and floor plan to understand association rules, rental permissions, insurance, recurring expenses, management needs, and the practical experience of arriving, staying, and leaving. With a clear plan, a Kihei second home can become a rewarding long-term part of your Maui lifestyle.
Thinking About a Second Home in Kihei?
Jyoti Graziano, REALTOR® (Hawaii License RS-81732), helps buyers assess ownership costs, association documents, permitted use, and South Maui property options that fit their lifestyle, budget, and plans, with particular expertise in condominiums, hotel-zoned properties, vacation rental rules, and Hawaii purchase contracts. Call +1 (808) 793-6181, email jyoti@mauiluxeproperties.com, or use the contact page to start your search. You can also browse current listings to see what is on the market.
What you get when you reach out:
- A custom search based on how you plan to use your second home
- Local insight on neighborhoods, rental rules, and HOA limits
- Referrals to lenders, inspectors, and property managers
FAQ
How much do I need to put down on a second home?
Second-home buyers often need a larger down payment than primary-home buyers, although the exact amount depends on the lender, loan size, credit profile, reserves, and property type. Buyers considering a Kihei condo should also ask whether the individual building affects available financing options.
Can I rent out my second home?
You may be able to rent a Kihei second home, but the answer depends on lender requirements, county rules, zoning, property classification, and the home's association documents. Verify the current requirements for the individual property before including rental income in your decision.
Is a second home a good investment?
A Kihei second home can support long-term ownership goals when personal use, carrying costs, and maintenance needs fit your plan. Enjoyment of the home, its location, and the ease of managing it from off-island may matter as much as potential financial return.
Can I use a VA or FHA loan for a second home?
VA and FHA financing generally serves primary-residence purchases rather than vacation or second homes. Buyers planning a Kihei second-home purchase should discuss conventional, jumbo, or other suitable financing options with a qualified lender.
FROM OUR BLOG
Culture Shift: What Surprises Buyers Moving to Kihei
Buyers moving to Kihei often discover that everyday routines, not beach access, define how well an address fits. The culture shift comes from island costs, a car-centered routine, weather-aware planning, and joining a community with deep local roots. A sunny condo near Kamaole Beach Park can still r
Kahului Outdoor Lifestyle: What Residents Say
Kahului outdoor lifestyle is built around everyday access to shoreline recreation, large public parks, sports facilities, and warm conditions throughout the year. Rather than relying on a resort-style setting, residents can fit a beach walk, youth practice, tennis session, dog walk, or picnic into a
Kihei Real Estate Market Report 2026
The Kihei real estate market in 2026 is bifurcated, with monthly sale-price medians moving sharply as the mix of condominiums, single-family homes, and higher-end South Maui properties changes. Kihei's recorded sales through July 2026 show a $959,500 median sale price across 654 sales, with monthly